Employees at Dallas-Fort Worth’s biggest employers, including Caterpillar, Toyota Motor North America, Charles Schwab, Lockheed Martin, and Texas Instruments, often find that their compensation letter comes with an acronym or two that salary alone never had. RSU. NSO. ISO. ESPP. Four sets of letters, four different tax rulebooks, and one pay stub that doesn’t explain any of it.
Most equity-comp articles online pick one of these and go deep. That’s useful once the applicable acronym is known, but a lot of DFW households sitting across from us hold two or three at once: RSUs from a current employer, leftover ISOs from a startup stint, and an ESPP through payroll. Before planning around any one of them, the map comes first.
Each of these runs on its own tax clock, and mixing them up when it’s time to file, or when deciding what to exercise or sell, is where the expensive mistakes start. What follows is a side-by-side comparison of how each award type is taxed, plus the three traps that cause the most damage in practice: AMT on ISOs, the 83(b) election window, and sell-to-cover math.
What’s the Difference in Taxes Between ISOs, NSOs, RSUs, and ESPPs?
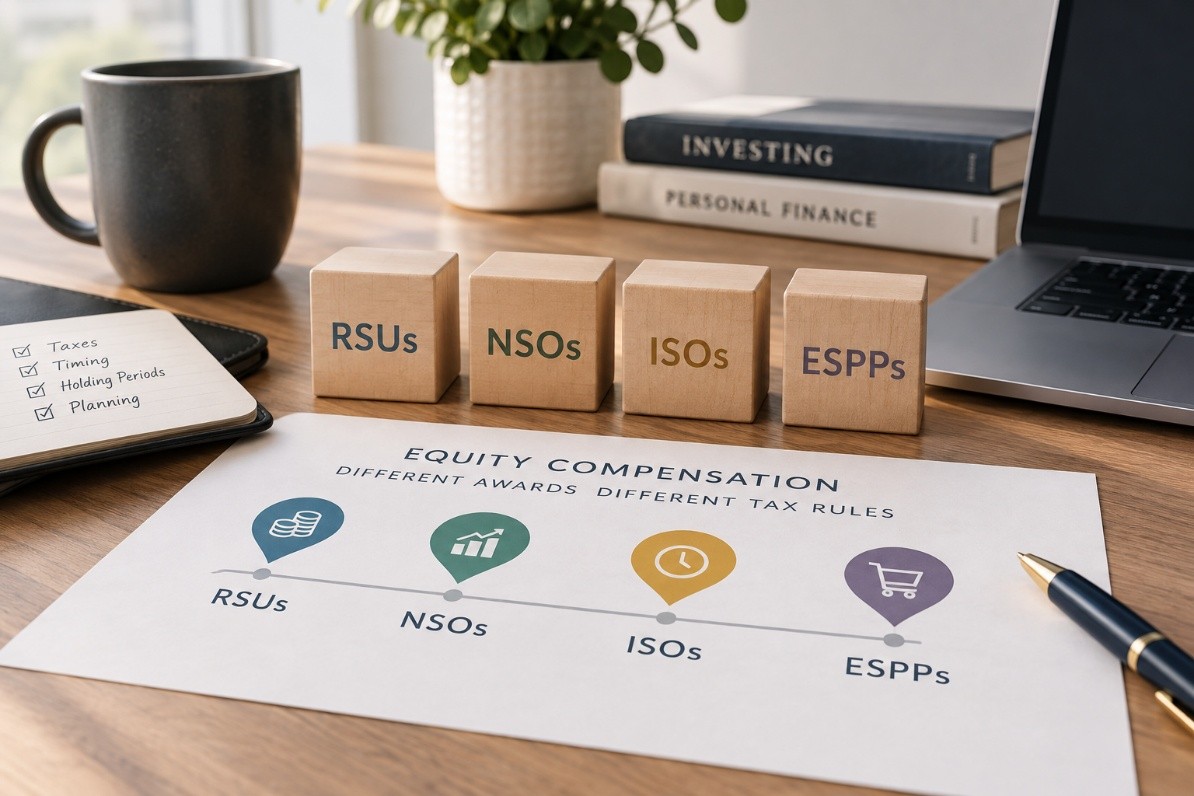
Equity compensation isn’t one thing with four names. Each award type has its own trigger for taxation, its own rate structure, and its own failure modes when it goes unmanaged.
Restricted Stock Units (RSUs)
RSUs are the simplest to understand and the easiest to mismanage. When shares vest, the full market value becomes ordinary income, reported on the employee’s W-2, whether or not any shares are sold. Employers typically withhold by selling some of the shares (more on that mechanic below). Any gain or loss after vesting is a separate, later capital gains event. Unvested RSUs are typically a different story: they’re usually forfeited if employment ends first. When Charles Schwab, headquartered just up the road in Westlake, cut roughly 2,000 jobs in late 2023 while integrating TD Ameritrade, that risk stopped being theoretical for a lot of DFW households holding unvested grants, and it’s a reminder that equity comp needs a seat at the table alongside the rest of a household’s financial plan, not an afterthought handled once a year.
Nonqualified Stock Options (NSOs)
NSOs generate ordinary income at exercise, based on the spread between the strike price and the stock’s fair market value that day. This is true even without a sale, since exercising alone can create a tax bill. Once exercised, the shares held start a new capital gains clock.
Incentive Stock Options (ISOs)
ISOs are the one award type that can avoid ordinary income tax altogether at exercise. If the shares are held long enough, generally more than a year from exercise and two years from grant, the entire gain can qualify for capital gains treatment. The catch is the alternative minimum tax, covered below.
Employee Stock Purchase Plans (ESPPs)
ESPPs let employees buy company stock through payroll deductions, often at a discount to market price. The tax treatment at sale depends on plan type and how long the shares were held. A qualifying disposition splits the gain between ordinary income and capital gains, while a disqualifying disposition pushes more of it into ordinary income. The discount itself is frequently taxed as compensation no matter what.
| Award Type | When It’s Taxed | What Kind of Tax | Watch For |
| RSUs | At vesting, on full share value | Ordinary income (W-2); capital gain/loss on later sale | Flat withholding rate often under-withholds |
| NSOs | At exercise, on the spread | Ordinary income; capital gain/loss on later sale | Exercise triggers tax even if shares aren’t sold |
| ISOs | Typically no regular tax at exercise | Capital gain if holding periods are met; AMT exposure at exercise | The AMT bargain-element trap |
| ESPPs | At sale, based on plan type and holding period | Mix of ordinary income and capital gain, depending on qualifying vs. disqualifying disposition | Discount is often taxed as ordinary income regardless |
Incentive Stock Options and the AMT Trap
The alternative minimum tax exists to make sure high earners with large deductions or exclusions still pay a baseline amount of tax, and the bargain element on an ISO exercise (the spread between strike price and fair market value) is exactly the kind of item AMT targets. Here’s the trap: a substantial AMT bill can come due in the year of exercise, calculated on paper gains from shares that are still held and unsold. If the stock later drops before it’s sold, tax may have been paid on a gain that no longer exists.
2026 sharpened this considerably. The One Big Beautiful Bill Act made the larger AMT exemption permanent but reset the income levels where that exemption starts disappearing, dropping them to $500,000 for single filers and $1,000,000 for joint filers, down from roughly $626,000 and $1,253,000 in 2025. It also doubled the speed of the phaseout, from 25 cents to 50 cents of exemption lost per dollar of income above the threshold. The practical effect is that an ISO exercise that produced a tolerable AMT bill last year can produce a much larger one this year, at the same income and the same bargain element.
This is precisely why ISO exercises should be modeled before the deadlines that close out the tax year, not discovered at tax time. The right exercise amount often depends on other income in that tax year, how much AMT credit is carrying forward, and whether a partial exercise across two tax years reduces the total bill.
The 83(b) Election: A Small Form With Big Consequences
Anyone who early-exercises stock options or receives restricted stock that hasn’t vested yet can file an 83(b) election with the IRS within 30 days of the grant or exercise. Doing so shifts the tax bill to today’s value, often close to zero right at grant, rather than to the (presumably higher) value at vesting.
The upside can be significant: future appreciation is taxed at capital gains rates instead of ordinary income rates, and the clock on long-term treatment starts immediately. The downside is real too. The election is irrevocable, and if the employee leaves the company or the stock never appreciates, tax has already been paid on value that was never realized. This isn’t a decision to make from a blog post; it’s one to run past an advisor and a tax preparer before the 30-day window closes.
Sell-to-Cover: What Actually Happens When RSUs Vest
Most employers handle RSU tax withholding through sell-to-cover: on vest day, a portion of the shares is automatically sold to cover the tax bill, and the rest land in the employee’s account. It feels automatic, and in one sense it is, but the flat withholding rate applied at vest frequently doesn’t match an employee’s actual marginal bracket. Just how large that gap can get and what to do about it before the next vesting date is worth walking through in more detail than fits here.
What sell-to-cover changes day to day is cost basis, not the size of the tax bill itself. The shares withheld for taxes are gone, and the shares that remain carry a cost basis equal to their value at vest. Brokerage 1099s sometimes report this basis incorrectly, defaulting to zero and overstating the gain if it isn’t corrected before filing. That’s one of the more common, and expensive, errors we catch when reviewing a new client’s tax return.
When You’re Holding More Than One Type at Once
The real complexity shows up when these four types stack. A large RSU vest can push an employee into a higher bracket right as an ISO exercise would otherwise make sense, or it can eat into the room available to exercise ISOs without triggering AMT. An ESPP purchase window that overlaps with a stock option exercise creates two separate holding-period clocks to track at the same time.
This is the pattern we see with long-tenured employees at DFW’s larger employers: years of stacked, overlapping grants, each running on its own vesting and holding-period clock, none of which show up together on a single statement. Untangling which clock governs which shares is usually the first step before any of the strategies above can be applied correctly. Anyone who also holds employer stock inside a 401(k) has yet another clock to track, one governed by a different set of rules around unlocking that stock at capital gains rates rather than anything covered here.
Sequencing an Equity Event Against the Rest of the Return
None of these awards get taxed in a vacuum. A large RSU vest or ISO exercise lands on top of salary, bonus, and whatever else is happening that tax year, and that combination is what determines the marginal rate, the AMT exposure, and whether bunching deductions or timing a Roth conversion makes sense.
Do You Need a Financial Advisor for Stock Options?
Which strategy makes sense, whether that’s exercising early, filing an 83(b), timing a sale, or simply holding, depends on income, other equity awards, risk tolerance, and the specific terms of the company’s plan. Once more than one award type is in the mix, or the dollar amounts are large enough that a mistake is expensive, that’s usually the point where a second set of eyes pays for itself. This kind of equity-comp mapping is part of the broader tax planning work we do alongside a client’s CPA year-round, not just at filing time. Anyone with RSUs, stock options, or an ESPP through a DFW employer can schedule a 15-minute intro call with Mills Wealth Advisors. The best time to plan is before the shares vest, the options are exercised, or the stock is sold, while there are still choices to make.